

On April 16th, 2024, Canada’s Finance Minister Chrystia Freeland proposed a budget that entailed $52.9 billion in new spending over five years (the “Bill”). The topic Pacific Legal will be discussing here would be the capital gain tax implication (the “New Tax Rule”) that was proposed in the Bill. For those unfamiliar with capital gain tax, a capital gain tax is the tax that a government charges when an individual or an entity sells a capital property more than the adjusted cost base.
The proposed Bill recommends an increase of the capital gains inclusion rate from 50% to 66.7% for corporations and trusts, and from 50% to 66.7% on the portion of capital gains realized annually that exceeds $250,000 for individuals. Although the Bill stipulated that this New Rule would only impact 40,000 individuals and 307,000 companies in Canada, the gravity of those impacted can’t go unnoticed, as the New Rule would generate around $19 billion in tax revenue over five years.
On one hand, as few Canadians support the Bill, there are many certain entities, young entrepreneurs, including high-net-worth individuals (the “Entrepreneurs”) who have demonstrated dissimilar reactions to it. This Bill has certainly raised eyebrows and has sent shock waves to people impacted by it. It’s notable and ironic that even Canada’s former finance minister Bill Morneau has outright opposed the New Rule stipulating that it would discourage investment by companies and job creators.
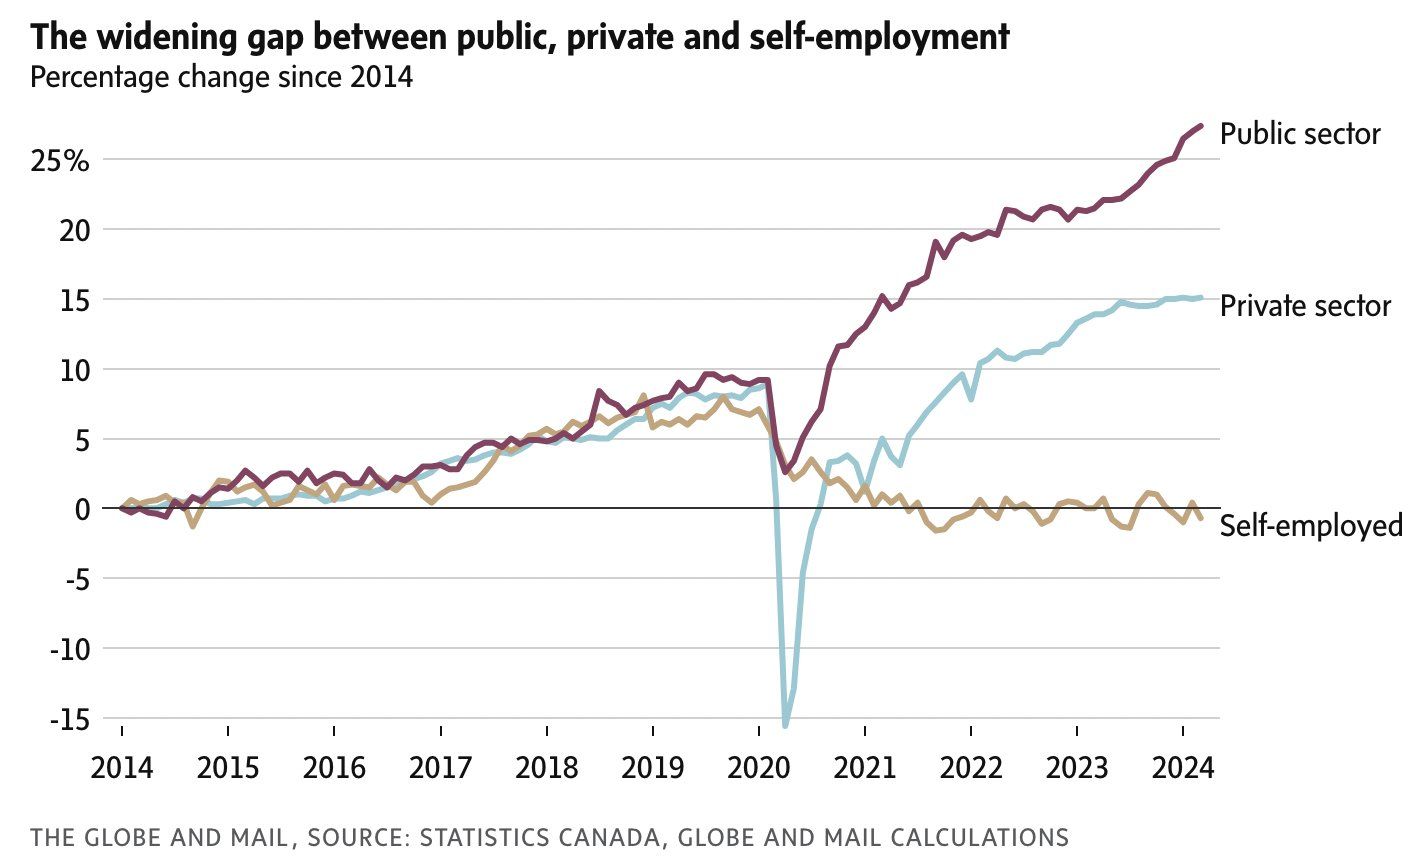
It won’t be incorrect to mention that Canada is already facing unprecedented emigration and reverse immigration where many Entrepreneurs are migrating to other promising destinations for tax benefits. It is pertinent to mention that this New Rule may drive Entrepreneurs to seek alternative routes such as Panama or Paraguay offering zero or negligible tax structures. Many Entrepreneurs, facing the wrath of this New Rule, feel punished for being furious risk-takers and being successful. At last, Pacific Legal believes that the New Rule may discourage investment by companies and job creators, and potentially witness more emigration among Entrepreneurs. If you are an Entrepreneur and if you are likely to be impacted by this New Rule, feel free to contact our office for international legal structuring, exploring territorial tax structure, and moving your investments overseas.
Details follows: Avi Khanna Partner: Pacific Legal Law Firm
Ph: +1 416.688.5567
Email: Avi@pacificlegal.ca
Website: https://pacificlegal.ca/